GST & ITC Reconciliation
Differences between GSTR-2B, purchase registers, vendor records, and accounting data.
GST & Construction Finance Consulting
With 23+ years of Finance & Accounts experience across construction and manufacturing, I help businesses strengthen financial controls, investigate GST reconciliation issues, improve project cost visibility, and prepare decision-ready management reports.
23+ Years of Finance & Accounts Experience|Construction & Manufacturing|GST & Financial Controls
Client Problems I Investigate
Differences between GSTR-2B, purchase registers, vendor records, and accounting data.
Organising invoice-level evidence, identifying disputed items, and preparing structured issue-wise responses for professional review.
Limited visibility into WIP, actual costs, estimated cost to complete, and forecast final margins.
Uncertified bills, overdue receivables, retention amounts, and gaps between billing and cash realisation.
Inconsistent reports, manual reconciliation, missing data, and delayed management insights.
Opportunities to improve repetitive analysis, exception tracking, reporting, and finance documentation through controlled AI-assisted workflows.
Let's identify the financial issue that needs attention.
Take the Next Step on WhatsAppConsulting Services
Each engagement is scoped individually after understanding your records, systems, and the specific issue. Scope, fees, timelines, and deliverables are agreed in writing before work begins.
A structured review of input tax credit position, invoice-level mismatches, and supporting evidence.
ITC eligibility and tax positions depend on applicable law, source documents, and the individual facts of each case. This service supports analysis and documentation; tax positions must be verified with your tax advisor.
Organising notice responses issue by issue, with reconciled numbers and a documented evidence trail.
This service does not promise notice cancellation, tax savings, or a favourable departmental outcome. Final replies should be reviewed and signed off by your legal or tax professional.
Project-wise financial control: WIP, cost to complete, and where margins are actually going.
Closing the gap between work done, bills raised, and cash actually received.
Decision-ready management reporting built on reconciled, traceable data.
Controlled, human-reviewed AI-assisted workflows for repetitive finance analysis.
Proposed offering under development. Not a live product, and not yet deployed with any client. Engagement concepts are discussed case by case.
How I Work
A structured enquiry first: what the business question is, which records exist, which systems produced them, and what decision the answer should support.
Reconcile sources and confirm cut-off dates before drawing conclusions. Analysis built on unverified data produces confident, wrong answers.
Differences are classified into a closed, defined set of categories with owners and follow-up status — so month-on-month progress is measurable.
Working papers with traceability, issue-wise summaries, and dashboards your team can maintain — not a presentation that cannot be reproduced.
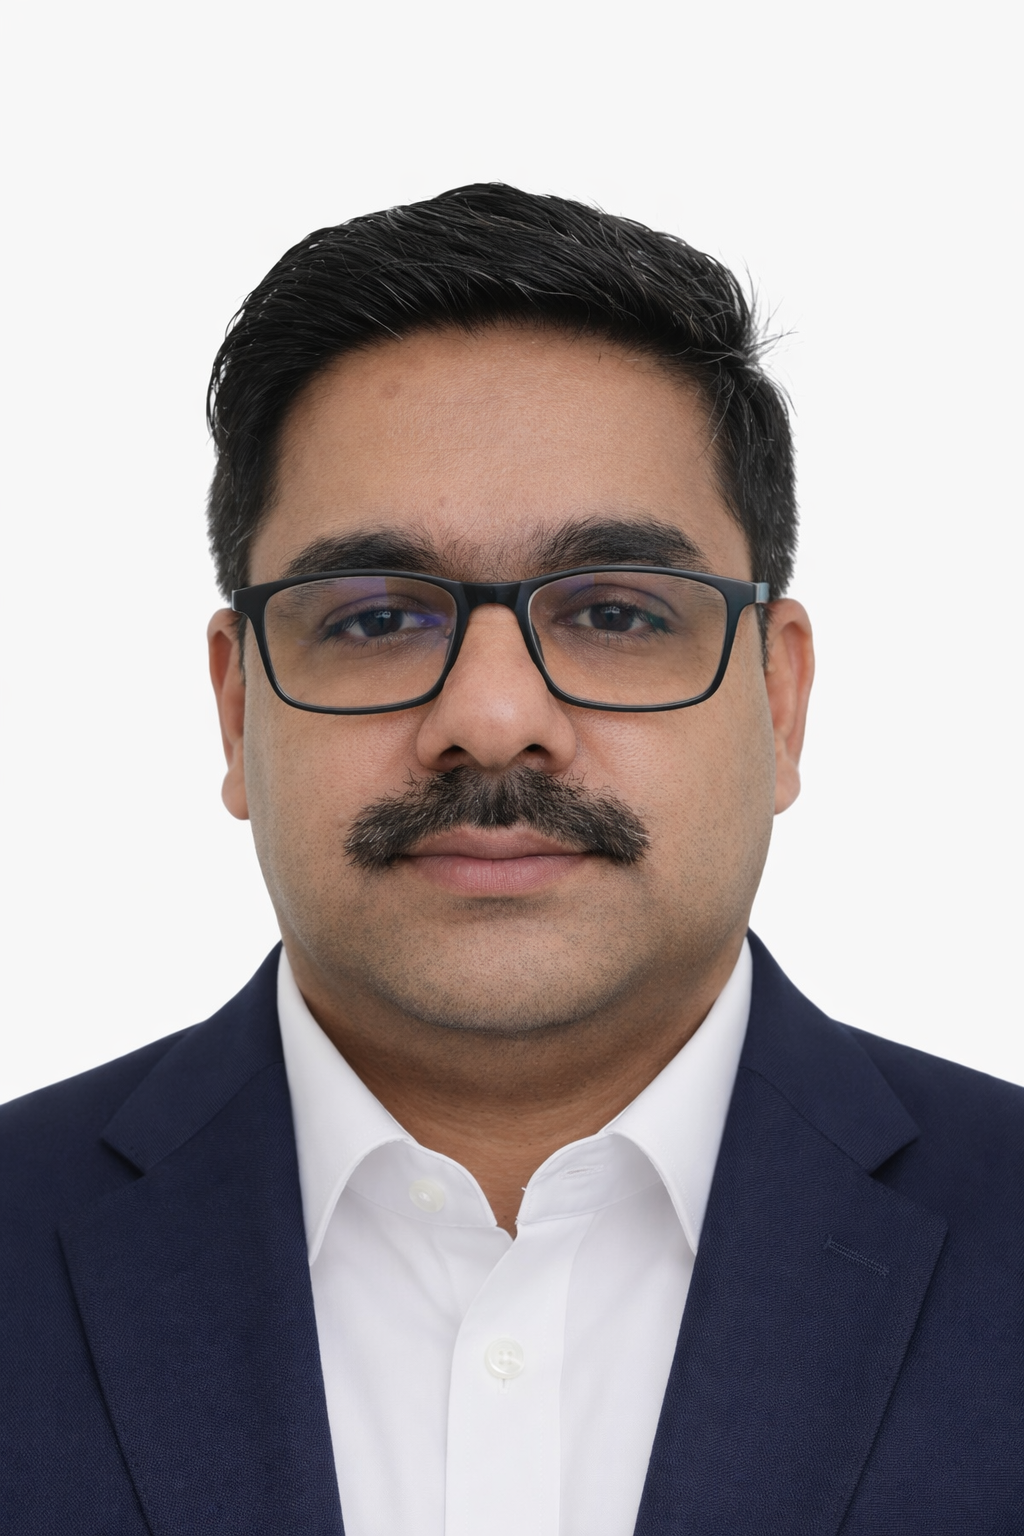
About
Over 23 years of hands-on Finance & Accounts experience in construction and manufacturing — project financial control, GST reconciliation and compliance support, working capital management, and management reporting. I work directly with finance heads, business owners, and site teams, and I distinguish clearly between what a review establishes and what requires your tax or legal professional.
Join B. Mohan Babu on WhatsAppDemonstrations
Illustrative walkthroughs of three engagements, showing the business question, the inputs, the analysis, the exceptions found, and the recommended next steps.
ILLUSTRATIVE DEMONSTRATION — NOT ACTUAL CLIENT DATA OR RESULTS.
Business question: Why does the input tax credit in our books differ from the credit reflected in GSTR-2B, and which differences need vendor follow-up?
Inputs
Analysis
Each invoice line is matched between GSTR-2B and the purchase register on GSTIN, invoice number, and tax amount. Differences are classified into a closed set: missing in 2B (vendor not filed), missing in purchase register (booking gap), amount/GSTIN mismatch, or duplicate. The table below shows a sample of the resulting match status.
Exceptions found
Next steps
| Invoice | GSTIN | 2B ITC (₹) | Books ITC (₹) | Status | Action |
|---|---|---|---|---|---|
| INV-1042 | 29AAAC… | 18,000 | 18,000 | Matched | None |
| INV-1109 | 27AABF… | — | 22,400 | Missing in 2B | Vendor follow-up |
| INV-1155 | 33AACD… | 18,800 | 18,800 | Matched | None |
| INV-1201 | 36AAAF… | — | 18,800 | Missing in 2B | Vendor follow-up |
| INV-1233 | 29AAAC… | — | 18,000 | Missing in books | Correct booking |
| INV-1287 | 06AABB… | 12,600 | 12,600 | Matched | None |
| INV-1302 | 24AAGH… | — | 21,340 | GSTIN mismatch | Reclassify |
Illustrative sample only. ITC eligibility depends on applicable law, source documents, and the facts of each case — a reconciliation identifies candidates for review, it does not establish eligibility.
Continue the Conversation on WhatsAppProfessional Insights
These articles are general educational material, current as of the date shown. They are not case-specific professional advice and do not create a client relationship. For your own facts, verify positions against the latest primary sources (such as notifications and circulars at cbic-gst.gov.in) and consult your tax or legal professional.
Why GSTR-2B, purchase registers, vendor records, and books diverge — and the control points that keep input tax credit reconciled month after month.
Read articleA repeatable structure for identifying issues, reconciling amounts and periods, assembling evidence, and preparing a draft reply for professional review.
Read articleHow to build a cost-to-complete estimate that actually forecasts final margins — budgets, actuals, commitments, and the discipline of updating estimates.
Read articleConnect on WhatsApp
Interested in GST, construction finance, financial controls or AI-assisted finance workflows? Join my WhatsApp group and connect with me there.
Open the Invite & Join the GroupWhatsApp will show the group invitation before you join. Your phone number may be visible to other members. Do not share passwords, bank credentials, Aadhaar numbers or confidential financial records in the group. Group participation is not a private consulting engagement or case-specific professional advice.